Car Leasing Explained: The Complete Guide to Leasing vs. Buying
Updated October 18, 2026 · Expanded education center | Lexus of Concord | Educational lease estimates for California shoppers
Lexus Leasing Education Center: Money Factors, Residual Values, Lease Programs & Payment Calculator
Learn how Lexus leasing works with our Pizza Theory, clear explanations of money factors and residual values, mileage programs, California taxes, and lease-end options. When you are ready, try the interactive lease payment calculator at the bottom of this guide.
The Pizza Theory: Leasing vs. Buying a Lexus
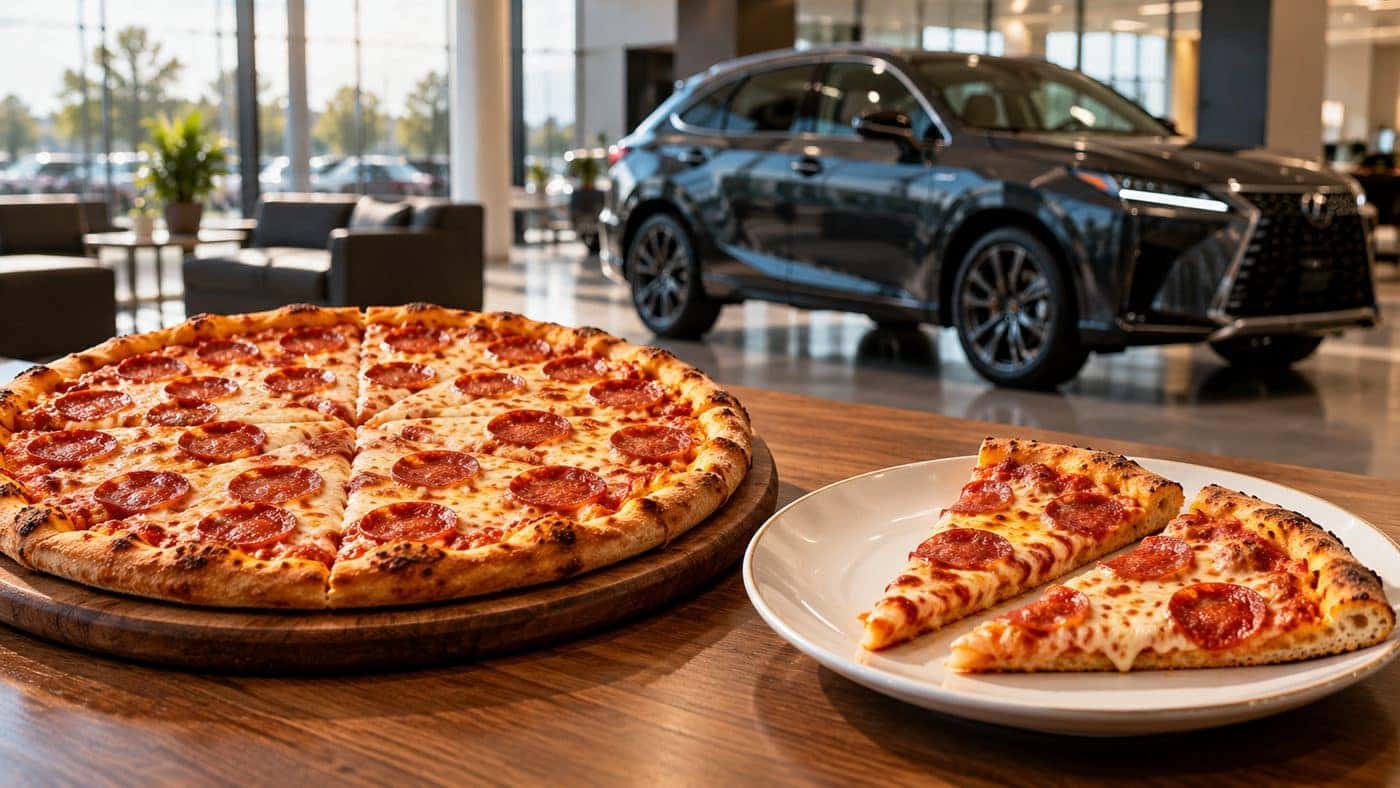
Why buy the whole pizza when you only plan to enjoy a few slices? Buying individual slices may cost more per slice than buying an entire pizza. But if you only want a few slices, your total bill may be lower—and you avoid paying for food you would not eat. Taxes can also affect the final bill.
Buying a Lexus is like buying the whole pizza. You pay for the entire vehicle and, once any loan is paid off, you own it outright. Unlike leftover pizza, however, a vehicle can retain meaningful resale or trade-in value. That remaining value is not simply thrown away.
Leasing a Lexus is like paying for the slices you expect to enjoy. Rather than purchasing the entire vehicle, you generally pay for its projected depreciation over the lease term, plus a financing (rent) charge, applicable taxes, and fees. The cost per year of use may be higher than keeping a purchased vehicle for many years, yet leasing may reduce your near-term cash outlay if you prefer driving a newer Lexus every few years.
And what about tax? In California, tax on a vehicle purchase is generally based on the taxable purchase price, whereas tax on a typical vehicle lease is generally collected on taxable lease payments and certain upfront amounts. This does not mean leasing is tax-free or always cheaper; your actual tax treatment depends on the transaction.
The takeaway: Sometimes a few slices cost more per slice but less in total. Likewise, leasing can be a smart fit for some drivers—but compare the full lease cost with the cost of buying, including eventual resale value, financing, taxes, fees, mileage, and how long you intend to keep the vehicle.
Example: $60,000 MSRP and a 60% residual equals a $36,000 projected lease-end value. That does not mean every lease customer pays exactly $24,000: the negotiated selling price, cap-cost reductions, money factor, term, taxes, and fees also matter.
What Is a Money Factor on a Car Lease?
A money factor is the number a leasing company uses to calculate the lease’s monthly finance or rent charge. It is not itself an APR. A commonly used approximation converts a money factor into an annualized interest-rate equivalent by multiplying by 2,400.
Monthly rent charge = (adjusted capitalized cost + residual dollar value) × money factor. Monthly depreciation = (adjusted capitalized cost − residual dollar value) ÷ lease months. Base monthly payment is the sum of those two components, before applicable taxes and other charges.
Who Sets the Money Factor and Residual Value?
Leasing financial institutions, such as Lexus Financial Services, establish lease programs, including residual schedules and base money factors, sometimes supported by manufacturer incentives. The lender’s residual value for a given vehicle, term, mileage allowance and program is not negotiable by the customer or dealership. The dealer may be permitted to adjust the money factor within lender guidelines, and credit qualifications or program changes can affect the applicable factor.
Residual value is a forecast of the vehicle’s value at lease end, generally stated as a percentage of MSRP, not the negotiated selling price. Leasing companies consider historical resale values, expected market demand, vehicle characteristics, age, mileage, and forecasts. Higher residual values generally reduce the depreciation component of a lease payment, all else equal. The residual is not a guarantee of what a dealer will pay for the car at lease end.
What Lease Mileage Programs Are Available?
Depending on the current Lexus Financial Services program, vehicle and lease term, available annual mileage allowances may include ultra-low mileage, low mileage and standard mileage options. The labels and available mileage tiers vary. Use the calculator’s mileage selector to plan your driving needs, but enter the actual lender residual percentage for the selected tier: changing the mileage dropdown does not invent or automatically adjust a residual.
| Example annual allowance | How to think about it |
|---|---|
| 5,000 miles | Ultra-low mileage, if eligible; best for very limited driving |
| 7,500 miles | Low-mileage option, where available |
| 10,000 miles | Common lower-mileage choice |
| 12,000 miles | Common middle-ground choice |
| 15,000 miles | Traditional standard-mileage reference |
Other programs may include single-payment leases or multiple-security-deposit programs when offered and eligible. Contact Lexus of Concord to confirm current availability and program rules. An advertised mileage tier is not a guarantee that it is offered for every model or lease length.
36-Month Lease: Do I Make 35 or 36 Payments?
A standard 36-month lease typically requires 36 scheduled monthly payments total. The first payment is normally collected at signing, leaving 35 future monthly payments. It is not a free month, and the lease is not a 35-month contract.
What Do I Pay Upfront on a California Lexus Lease?
Cash due at signing is not the same as a down payment. It can include the first monthly payment, acquisition fee, DMV/registration, applicable taxes, dealer charges and any optional cap-cost reduction.
| Item | Calculator treatment |
|---|---|
| First monthly payment | Collected at signing; included in total 36 payments |
| Acquisition fee | $895 illustrative assumption; may be paid upfront or capitalized if permitted |
| Documentation fee | $85 dealer fee assumption |
| Electronic registration fee | $37 dealer fee assumption |
| DMV/registration | Editable estimate; actual amount varies |
| Applicable California taxes | Estimated monthly tax plus separately entered upfront taxes where applicable |
| Down payment | Optional cap-cost reduction, not the entire signing amount |
For budgeting, some customers may see approximately $1,500–$4,000 or more due at signing depending on the vehicle, location, fees, tax treatment and down payment. This is a broad illustration, not a mandatory minimum or a dealer quote. California generally taxes periodic lease payments, with additional rules for upfront payments and certain charges; the exact amount depends on the transaction.
Should I Put Money Down on a Lease?
A larger cap-cost reduction usually lowers the monthly payment, but it increases your upfront cash commitment. Consider comparing $0 down, $2,000 down and $5,000 down using the calculator. If the vehicle is stolen or declared a total loss, a large upfront cap-cost reduction may not be recoverable. Compare total lease outlay and cash-flow needs, not just the advertised monthly payment.
What Happens at the End of a Lexus Lease?
Depending on your contract and lender rules, you can generally return the vehicle, purchase it under your lease purchase option, or replace it with another vehicle. A purchase may involve taxes, title/registration charges and applicable purchase-option fees. A return may involve excess mileage, excess wear, disposition charges and unpaid amounts. Early termination can be expensive.
Read Lexus Financial Services’ vehicle return instructions and lease-end FAQs for official guidance.
Frequently Asked Lexus Lease Questions
Can I negotiate the residual value?
No. The lender-established residual for a specific vehicle, term, mileage and program is not negotiable by either the customer or the dealership. Selecting a different eligible program may produce a different residual.
Can I negotiate the money factor?
The lender establishes the underlying program and credit requirements. Dealers may have limited permitted adjustments. Ask for the money factor and an itemized written lease quote.
Does the residual use MSRP or the negotiated selling price?
Typically the applicable MSRP used by the lender, not the negotiated selling price. The negotiated price affects the adjusted capitalized cost.
Is the first month’s payment included in a 36-month lease?
Yes. Typically the first of 36 scheduled payments is due at signing, leaving 35 scheduled payments afterward.
Can I get a low-mileage Lexus lease?
Low and ultra-low mileage options may be available depending on the model, term and current lender program. Ask the dealership to verify the corresponding residual.
Are the acquisition fee and down payment the same thing?
No. The acquisition fee is a lender-related lease origination charge; a down payment is an optional capitalized-cost reduction.
Can I buy my leased Lexus at the end?
Generally yes, subject to the purchase-option terms in your contract. Your purchase option is distinct from a third-party dealership’s ability to pay off the lease directly.
Can I return my Lexus lease to any dealership?
Lexus Financial Services requires returns to authorized Lexus or Toyota dealers. Your originating dealer must process your return; contact other authorized dealers ahead of time to confirm they will accept it.
What if I exceed my mileage allowance?
Your contract specifies excess-mileage charges. Mileage allowances should be chosen based on realistic expected driving.
What is the difference between a lease payment and total lease cost?
The monthly payment alone does not include all upfront cash and potential lease-end costs. Compare the total of scheduled payments, nonrefundable signing charges and any expected lease-end charges.
Lease vs. Finance vs. Cash: Which Fits Your Situation?
| Question | Lease | Finance | Cash purchase |
|---|---|---|---|
| Who owns the vehicle during the agreement? | Leasing company | Buyer, subject to lender lien | Buyer |
| Typical monthly payment | Often lower for a comparable vehicle and term | Often higher at a comparable term | No monthly loan payment |
| Mileage limits | Contractual allowance and possible excess charges | No contractual lease mileage limit | No contractual lease mileage limit |
| Equity/ownership | No automatic ownership; purchase option may apply | Equity depends on market value and loan balance | Owner retains vehicle value |
| End of term | Return, purchase, or replace subject to contract | Keep, trade, or sell | Keep, trade, or sell |
| Best comparison | Compare total cash outlay, remaining value/equity, taxes, and your expected use—not monthly payment alone. | ||
Excess Mileage Estimator
Estimate a possible end-of-lease mileage charge using the rate stated in your signed agreement. Unused mileage typically does not generate a refund unless a specific program says otherwise.
This is a planning estimate, not an official payoff or end-of-term bill. Confirm odometer allowance, any starting mileage adjustments, and contracted rate.
How to Read Your Lexus Lease Agreement
| Term | Plain-English meaning |
|---|---|
| MSRP | Manufacturer’s suggested retail price; commonly the basis for residual calculations |
| Agreed-upon value | Negotiated vehicle selling price used in the lease calculation |
| Gross capitalized cost | Vehicle price plus permitted capitalized fees, products, and other amounts |
| Cap-cost reduction | Cash, applicable rebates, or trade equity used to reduce financed lease cost |
| Adjusted capitalized cost | Gross cap cost after applicable reductions |
| Residual value | Predetermined contractual projected lease-end value; not a negotiable price |
| Rent charge | Financing cost built into lease payments |
| Acquisition fee | Lender origination charge; verify actual amount and whether paid upfront or capitalized |
| Disposition fee | Potential charge on return, if stated in the contract; waivers may depend on program |
| Purchase option | Contractual right, when available, to buy at the specified terms plus applicable charges/taxes |
| Early termination | Contractual costs and obligations for ending before scheduled maturity |
Why Might My Advertised Payment Differ From My Quote?
Advertisements can assume a particular model and MSRP, lender approval tier, lease term, annual mileage, cash due at signing, incentives, and tax treatment. A personalized quote also reflects your negotiated selling price, actual credit approval, trade equity or negative equity, DMV fees, optional products, and current programs. Ask for an itemized lease worksheet rather than comparing payment figures in isolation.
What If My Leased Lexus Is Totaled or Stolen?
Contact your insurer and leasing company promptly. The insurer’s settlement may differ from the contractual payoff. Some leases include a GAP waiver or similar protection, but exclusions, deductibles, late amounts, and other obligations may remain. Do not assume a large down payment will be refunded after a total loss; this is one reason to compare low-down-payment lease structures. Read the actual insurance and lease terms.
Your Lease-End Roadmap
| When | What to do |
|---|---|
| 90–60 days before maturity | Review contract, mileage, tires, maintenance, wear standards, and current buyout or replacement options |
| 60–30 days before maturity | Ask about inspection procedures, return scheduling, purchase-option price and financing if buying |
| At maturity | Return to an eligible accepting location, purchase under contract, or arrange replacement; document odometer and return receipt |
| After return | Review final statement for any excess mileage, wear, disposition or other contractual charges |
California Lease Tax & Fee Education
California generally taxes lease payments for tangible personal property, including vehicles, with rules for certain upfront amounts and purchases. The exact tax rate and treatment depend on the transaction and location. A lease-end purchase can create a separate taxable purchase. DMV/title/registration fees vary. The calculator’s $85 documentation, $37 electronic registration, and $895 acquisition entries are editable examples, not a promise that every transaction uses those amounts. Request a line-by-line itemization of first payment, registration, acquisition fee, applicable taxes, and any cap-cost reduction.
Lease Knowledge Check — Customers & Employees
Choose the best answer, then select Check Answers. This quiz teaches the basics; internal lender rules should be verified separately.
1. Who sets the contractual residual value?
2. A 36-month lease with first payment due at signing normally has how many remaining scheduled payments?
3. Money factor × 2,400 gives:
4. Is an acquisition fee the same as a down payment?
5. What should customers compare between two lease offers?
Real-World Leasing Scenarios
I drive 20,000 miles per year. Is a low-mileage lease a good fit?
Probably not without careful calculation. Compare available higher-mileage allowances with projected excess-mileage charges and a purchase alternative. A low advertised payment can be misleading when the mileage allowance does not fit your driving.
I have negative equity in my trade. What changes?
If the lender permits negative equity to be added to the lease, the adjusted cap cost and monthly payment generally rise. Show the trade allowance and payoff separately and explain the effect before signing.
I plan to buy my Lexus at lease end. Should I still lease?
Compare the total lease payments plus purchase-option amount, fees, taxes and any subsequent financing against purchasing upfront. Leasing first is not automatically cheaper.
Should I put $5,000 down to reduce my payment?
A larger cap-cost reduction generally lowers the monthly payment, but it raises upfront exposure. Compare total cash outlay and understand total-loss treatment before deciding.
More Frequently Asked Questions
Can I negotiate the money factor?
The base money factor is set by the lender’s program, but an allowable dealer adjustment may be possible. Ask for the money factor on the actual quote and compare total lease costs.
Can I negotiate my Lexus residual value?
No. The lender-established residual for a given lease program is not negotiated by the customer or dealership. Selecting a different eligible term, mileage allowance, or vehicle may change the applicable residual.
Do I have to service my Lexus at the selling dealership?
No. Follow the required maintenance schedule and contract requirements, keep records, and use qualified service providers. Separate prepaid maintenance contracts may have their own conditions.
Can I terminate my lease early?
Often there are early termination or payoff procedures, but substantial costs may apply. Ask the leasing company for a current written quote rather than assuming remaining payments equal the payoff.
Can I extend my lease?
Extensions, if available, depend on lender rules and your account. Ask Lexus Financial Services for current options and written terms.
Authoritative Resources & Employee Reference
For current program eligibility, exact residuals, money factors, credit approvals, and dealer procedures, consult current Lexus Financial Services materials rather than relying on this educational example. Public resources: Lexus Financial Services, California DMV, and California Department of Tax and Fee Administration.
Employee guidance: Use the calculator for education, not as an approved quote. Verify program bulletins, current lender terms, customer credit qualification, and actual fees in authorized systems. Never publish internal rate sheets, private credit tiers, or confidential program documents on this page.
Try the Lexus Lease Payment Calculator
Now that you understand the terms, use this educational calculator to explore how price, money factor, residual value, mileage, taxes and fees affect your estimated lease payment.
Interactive Lexus Lease Payment Calculator
Dealer fee assumptions: $85 documentation + $37 electronic registration. These are dealer charges, not government fees. DMV is a user-editable estimate. The tax rate is a user-entered assumption; actual California lease taxation may require additional upfront taxes and treatment of incentives or cap-cost reductions.
| Residual dollar value | — |
|---|---|
| Adjusted capitalized cost | — |
| Monthly depreciation portion | — |
| Monthly rent / finance charge | — |
| Monthly payment before tax | — |
| Estimated monthly tax | — |
| Money factor approximate APR equivalent | — |
| Remaining monthly payments after signing | — |
| Total scheduled lease payments | — |
| Estimated allowed lease miles | — |
Total lease outlay includes all modeled scheduled payments, the cap-cost reduction, applicable acquisition/dealer/registration charges paid at signing and other entered upfront costs. It excludes insurance, fuel, maintenance, potential end-of-lease charges, refundable deposits and any tax or fee not entered. Rebates are assumed to reduce the adjusted capitalized cost and may be taxed differently in actual contracts. Negative trade equity is added to cap cost; positive trade equity is treated as a cap-cost reduction. Figures are approximate and rounded for display.
Get a Personalized Lexus Lease Quote in Concord, California
Our team can help you compare lease terms, eligible mileage programs, current incentives, residuals, money factors and the actual amount due at signing. Browse our inventory or contact Lexus of Concord for a vehicle-specific quote.
Shop New Lexus InventoryContact Lexus of Concord
Calculator and advertising disclaimer: All amounts are illustrative estimates only, not an offer, advertisement of specific available lease terms, credit approval or binding quote. No particular residual, money factor, mileage program, acquisition fee, incentive, or lender policy is guaranteed. Actual payments and cash due depend on vehicle, lender, customer qualifications, taxes, fees, current programs and signed documents. The displayed payment uses a simplified conventional lease formula; actual lender calculations, tax treatment, rounding, capitalized fees and payment schedules may differ. Confirm all figures, including California tax and registration, with the dealer and leasing company before signing.
0 comment(s) so far on Car Leasing Explained: The Complete Guide to Leasing vs. Buying